Opinion: Donating to a registered charity is not wrongdoing
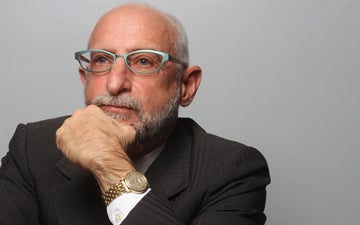
Canadian tax lawyer and accountant David J Rotfleisch on what a recent article by the IJF about the Asper Foundation gets wrong about Canadian charity law
On September 7, 2026, Canadian Accountant republished an Investigative Journalism Foundation piece reporting that the Asper Foundation gave more than $4.8 million over roughly two decades to charities whose registrations the Canada Revenue Agency later revoked. The story is presented as a tax and charities item, and it appears in this publication's practice and taxation sections. It is fair for accountants and tax professionals to read it that way and to ask whether it holds up as tax reporting.
In my view, it does not. The article does not dispute that the CRA made serious findings against several Israel-related charities, and neither do I. Those findings are on the public record, and some of them remain in litigation. My concern is with how the article connects those findings to a donor who is not accused of breaching any rule of the Income Tax Act. The connection rests on imprecise terminology, a misunderstanding of how qualified donee status works, selective treatment of pending litigation, and a line of reasoning that has more to do with a museum exhibit than with tax law.
Background: A Tax Audit Deployed as a Rebuttal to Criticism
The article's starting point is not a tax question at all. Gail Asper, whose family was instrumental in creating the Canadian Museum for Human Rights, publicly criticized the museum's 2026 exhibit on the displacement of Palestinians in 1948. Her criticism was specific: the exhibit, in her view, omitted essential facts about the conflict and contained inaccuracies. Her family foundation paused a planned $50,000 gift and asked for a review of how the museum chooses and presents its exhibits.
That is exactly the kind of criticism a national museum supported by public money and private donors should expect and answer on the merits. The article does not answer it. It does not identify a single fact Ms. Asper says was omitted, test a single inaccuracy she alleges, or ask the museum to respond to either. Instead, it goes through two decades of her family foundation's grant records to suggest that the critic is not entitled to be heard.
I have practised tax law for decades, and I recognize the technique. When the substance of a complaint is inconvenient, change the subject to the complainant. Here the subject was changed using CRA revocation letters about other organizations, none of which found any wrongdoing by the donor.
The quality of the exhibit is a question of history and curation. The foundation's grants are a question of tax law. Mixing the two produces neither good history nor good tax reporting.
Key Issues: Where the Article Goes Wrong
"Later sanctioned" is doing all the work
The headline says the foundation donated to groups "later sanctioned." The word "later" is the heart of the matter, and it cuts against the story.
Under the Income Tax Act, the question for a donor, and for the validity of an official donation receipt, is whether the recipient was a qualified donee when the gift was made. Each gift described in the article was made to an organization that was a registered charity at the time. Each was receipted. A private or public foundation making grants to registered charities in good standing is doing exactly what the charitable regime contemplates. A later revocation does not reach back and turn a lawful gift into an improper one.
The foundation's stated policy is to fund based on registration status and the recipient's charitable activities when a grant is approved, and not to fund organizations after revocation. That is the correct standard. The article reports the policy but does not engage with it, and it identifies no CRA finding of any kind against the foundation itself.
Revocation and sanctions are not the same thing
Accountants who work with charities know that the CRA's compliance toolkit is graduated. It includes education letters, compliance agreements, monetary penalties, suspension of receipting privileges, and, at the far end, revocation of registration. Separately, Global Affairs Canada imposes sanctions on foreign individuals and entities under an entirely different statutory scheme.
The article uses "sanctioned" loosely to cover CRA revocations and, later, a Global Affairs Canada designation of an Israeli group. Those are different legal outcomes with different legal consequences, made by different decision makers under different statutes. Merging them makes for a sharper headline but a less accurate tax story.
The Jewish National Fund revocation is contested, and the court record matters
The largest dollar figure in the article is the foundation's giving to the Jewish National Fund of Canada between 2005 and 2024. The CRA's allegations against JNF are detailed, and I do not suggest they should be ignored. But the article treats the revocation as settled, noting only in passing that JNF is challenging it.
A reader should know more than that. The Federal Court of Appeal has allowed JNF to amend its notice of appeal to plead bias, procedural unfairness and substantive error. The Court has found the certified tribunal record incomplete and ordered further production. In March 2026, in Jewish National Fund of Canada Inc. v. Canada (National Revenue), 2026 FCA 63, the Court refused JNF's request to allow the appeal outright as a remedy for the government's conduct, but found that the government had not fully complied with the June 2025 production order. It directed further searches for documents bearing on the bias allegation, including requests to the Commissioner's Office and the Minister's Office, and a further affidavit explaining how the searches were done.
As of late September 2026, the appeal is proceeding on an expedited schedule, JNF has filed its memorandum of fact and law, and no hearing date has yet been set.
None of those rulings decides the merits, and the Court said expressly that its March 2026 reasons have no bearing on the ultimate issues, which will go to the appeal panel. They do not restore JNF's registration and they do not establish bias. I want to be careful on that point because overstating a procedural win is as misleading as ignoring it. But an appellate court taking a bias allegation seriously enough to compel further disclosure from the regulator is plainly relevant to any article that relies on that regulator's conclusions as the foundation of its argument.
It is also relevant that JNF's position is that the CRA reversed course on a charitable object it had accepted in 1967, and revoked without meaningfully engaging with the new objects JNF proposed. That is a regulatory process story that practitioners in this field will recognize, and the article leaves it out.
What could a donor reasonably have known?
The article quotes an advocacy group representative who suggests that regular donors would have known about the ineligible activities, while conceding that not every donor did. That is speculation, and it sits awkwardly with the article's own facts.
Take the Canadian Zionist Cultural Association. The article reports that CZCA publicly described its work as grocery vouchers for families in need, programs for bereaved families and youth, and scholarships. The concerns the CRA raised, including shared premises, telephone numbers, staff and payroll with a separate organization supporting soldiers, came to light through a CRA audit. They were not advertised. A foundation reviewing CZCA's public description and its registered status would have seen a charity presenting legitimate programs.
The article also reports that the CRA first raised concerns about JNF in 1989 and flagged many of the same issues again in a 2016 audit, yet did not issue its notice of intention to revoke until 2019 and revocation did not take effect until 2024. If the regulator, with full audit powers and access to books and records, took decades to act, it is not reasonable to suggest that a grant-making foundation should have reached the same conclusion first. Due diligence is a real obligation, but it is measured against what a donor can see, not against what an auditor later finds.
Academic characterization is not a CRA finding
The article relies on a postdoctoral researcher who describes several of the charities as largely conduits for overseas funding and characterizes the charitable sector itself in sweeping terms. Researchers are entitled to their conclusions. But the only authoritative findings in the article are the CRA's own letters, and the article presents the academic's characterization alongside them without distinguishing between the two. The same researcher also acknowledges that many of the charities named supported recognized charitable causes, which undercuts the conduit label rather than supporting it.
The Mizrachi link rests on two degrees of separation
The weakest connection in the article concerns Mizrachi Canada. The foundation gave Mizrachi Canada about $120,000 in 2023 and 2024. Separately, over a five year period, Mizrachi Canada gave roughly $16,000 to an Israeli group that Global Affairs Canada has since sanctioned. The foundation did not make that grant.
More importantly, the CRA told the IJF directly that since Mizrachi Canada was registered in 1979, the agency has not suspended or penalized it and has not revoked or annulled its registration as the result of an audit. The regulator's own statement contradicts the implication the article draws. Linking a donor to a sanctioned foreign group through a Canadian charity in good standing, on the strength of a small grant the donor did not make, is association rather than analysis.
Practical Implications for Donors, Foundations and Their Advisors
For those of us who advise foundations and major donors, the story is still useful, though not in the way its authors intended. It is a reminder that reputational exposure can arise from grants that were entirely lawful when made. That argues for documented grant approval processes, periodic checks of recipient status on the CRA's list of charities, review of recipients' public descriptions of their activities and of their filed information returns, and a written policy on what happens if a recipient's status changes.
It does not support the idea that a donor becomes responsible for a charity's later regulatory problems. That standard would make charitable giving unworkable, and it is not the law. Advisors should be prepared to explain that distinction to clients who read stories like this one and wonder whether their own past gifts are now in question.
Takeaway
The CRA's findings against several Israel-related charities are serious, and some are still before the Federal Court of Appeal. They deserve careful, accurate reporting. What they do not support is the conclusion that a foundation which gave to registered charities in good standing, under a policy consistent with the Income Tax Act, has thereby disqualified itself from criticizing a museum exhibit. That is a rhetorical move, not a tax analysis. Canadian Accountant's readers understand the difference between a regulator's finding, a litigant's allegation, an advocate's opinion and a donor's lawful gift. Tax reporting should keep those categories separate.
David J. Rotfleisch, CPA, JD, is the founding tax lawyer at Rotfleisch & Samulovitch Professional Corporation in Toronto and a Law Society of Ontario Certified Specialist in Taxation. Author photo courtesy Rotfleisch & Samulovitch P.C. The views and opinions expressed in this article are those of the author. The content of this article is intended to provide a general guide to the subject matter.


(0) Comments